Entry in Staying on Your Parents' Car Insurance in College
College Car Insurance: Parents' Policy vs. Separate Policy
Deciding between keeping a college student on the family car insurance or buying an individual policy? Compare costs, discounts, liability, and coverage rules.
By Sophie Lindqvist · Editor
Published
Answer in brief
Staying on a parents' car insurance policy is almost always cheaper for college students than buying a separate policy because families benefit from multi-car discounts, multi-policy bundling, and shared liability limits. However, establishing a separate policy becomes necessary when the student permanently relocates, purchases a vehicle titled solely in their own name, or needs to shield parents from heightened liability exposure.
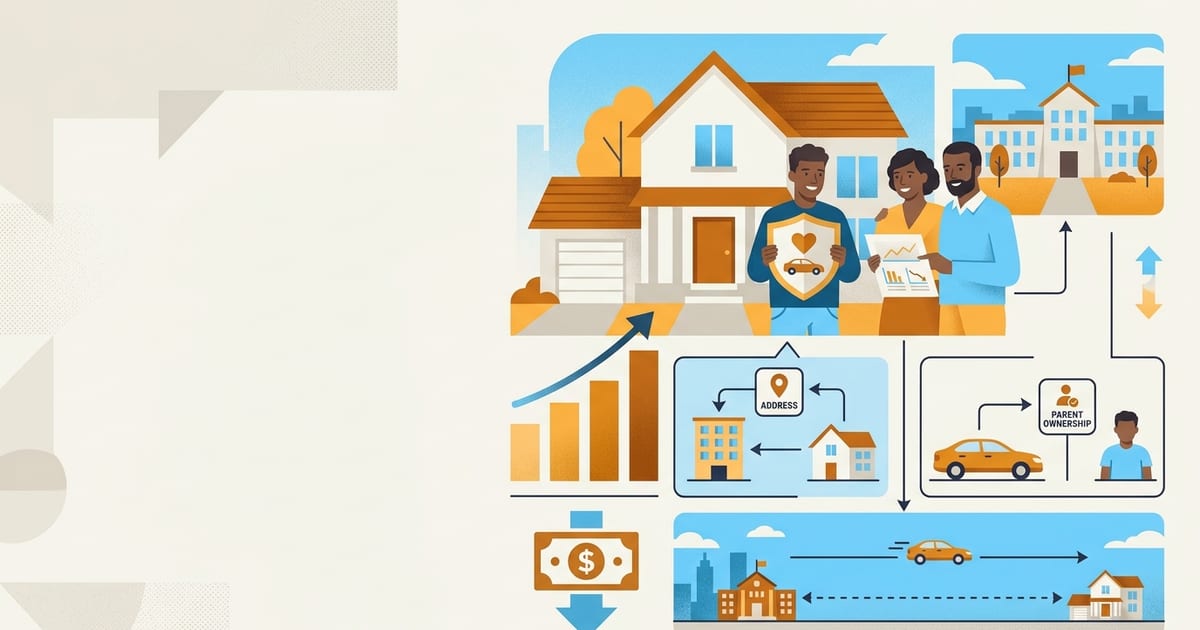
When a son or daughter leaves for university, parents and students face an immediate financial decision: should the young driver remain on the existing family auto policy, or is it better to purchase a separate individual policy? Auto insurance for young adults represents a major expense, making it critical to weigh household discounts against legal responsibilities and risk exposure.
Young drivers face significant insurance rating hurdles. Research published by the Insurance Institute for Highway Safety confirms that the fatal crash rate per mile driven for 16-to-19-year-olds is just over three times higher than the rate for drivers aged 20 and older. Because insurers price policies around risk, standalone coverage for a college undergraduate carries a substantial price tag.
Cost Comparison: Shared Family Coverage vs. Solo Policies
According to the Insurance Information Institute, adding a teen or college student to an existing parent policy is generally far more economical than purchasing a standalone policy. Family plans distribute risk across more experienced operators and unlock account-level discounts that single-vehicle student policies cannot access.
| Feature | Family Policy | Separate Policy |
|---|---|---|
| Relative Cost | Lower; shares policy credits | Higher; rated solely on young driver risk |
| Available Discounts | Multi-car, home bundle, good student | Good student only (if offered) |
| Parent Financial Risk | Parents share liability exposure | Parents isolated from student claims |
| Vehicle Title Rule | Vehicle usually titled to parents or joint | Vehicle titled solely in student's name |
| Address Requirement | Shared primary household residence | Student's independent address |
The National Association of Insurance Commissioners reported that the countrywide average expenditure for private passenger auto insurance reached $1,281 in 2023. However, an independent policy for an undergraduate can easily cost two to three times that figure, running an illustrative range of $2,500 to $4,500 annually depending on location, vehicle choice, and driving record. By contrast, retaining the student as an occasional driver on the family policy may add an illustrative $1,000 to $2,000 per year.
Key Discounts Available on Family Policies
A primary reason shared policies remain more affordable is the stacking of carrier discounts. The Insurance Information Institute notes that raising collision and comprehensive deductibles from $200 to $500 can cut physical damage costs by 15% to 30%, while choosing a $1,000 deductible can trim costs by 40% or more. Beyond deductibles, families can leverage:
- Multi-Car Discounts: Insuring the student's car alongside parental vehicles delivers per-vehicle rate credits across all household automobiles.
- Good Student Discounts: Full-time students who maintain academic benchmarks (typically a B average or 3.0 GPA) earn policy reductions through the good student discount.
- Distant Student Reductions: Undergraduates attending school more than 100 miles away without a vehicle can trigger major savings through the distant student discount.
- Multi-Policy Bundles: Pairing vehicle coverage with a parent's homeowner or umbrella policy yields broad policy discounts unavailable to an apartment renter.
When a Separate Policy Is Legally Required
Despite the cost advantages of staying together, specific legal and logistical conditions force a college student to obtain an individual auto insurance policy. Insurers enforce strict rules regarding insurable interest, vehicle titling, and residency definitions.
- 1
Check the vehicle title
If the vehicle title is in the student's name alone, many insurers will not permit it to remain on the parents' policy because the parents lack legal ownership interest in the asset.
- 2
Evaluate permanent residency
If the student has established permanent residence in their college town, signed a year-round lease, and changed their voter registration or tax filing, they are no longer part of the parental household.
- 3
Assess parental liability exposure
If a student has accumulated severe traffic citations or at-fault collisions, parents may opt to separate policies to insulate personal assets and home equity from future lawsuits.
- 4
Verify state insurance regulations
Under state financial responsibility frameworks, moving out-of-state permanently requires re-registering and re-insuring the vehicle under the host state's minimum requirements.
How to Transition to an Independent Policy Smoothly
If purchasing a standalone policy is the correct choice, careful timing prevents costly lapses in continuous coverage. Begin comparing rates at least 30 days before moving off the family policy. Use our quote comparison tool to evaluate standard and regional insurers side-by-side, taking care to select adequate liability limits rather than dangerous minimums.
When binding the new contract, coordinate the start date so it coincides precisely with the cancellation date on the family policy. Once active, provide proof of coverage to the parents' insurer so they can remove the student without penalty.
Questions & answers
Can a student stay on their parents' insurance if the car is at college?
Yes, provided the student remains a dependent resident of the household and the insurer is formally notified of the car's updated campus garaging address.
Whose name should be on the car title for a family insurance policy?
To keep a vehicle on a parents' auto policy, the title typically must include at least one parent's name, either as the sole owner or as a joint co-owner with the student.
Does removing a college student from a parent policy lower the premium?
Yes. Removing a youthful driver who is classified as a primary or occasional operator typically reduces the household premium significantly due to the lower statistical risk.
What happens if a college student on a family policy causes an accident?
The family auto policy will pay claims up to its liability limits. However, because the policy is held by the parents, their insurance record and renewal rates will reflect the claim.
Terms: Deductible, Premium, Occasional driver, Continuous coverage, Liability limits
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Companies may offer auto insurance discounts. No law requires discounts. — Texas Department of Insurance (2025)State insurance regulatorNo Texas law or rule mandates auto insurance discounts (for age, low mileage or anything else) or puts a time limit on them; advertising that says otherwise is misleading.
- Teenagers — Insurance Institute for Highway SafetyIndependent researchTeen crash risk, graduated driver licensing research and vehicle recommendations for young drivers.
- Fatality facts: Teenagers — Insurance Institute for Highway Safety (2024)Statistical dataFatal crash rate per mile driven for 16–19-year-olds is just over 3 times the rate for drivers 20 and older (2022 travel data); all-severity crash rate is over 4 times; risk is highest at 16–17.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- Facts + Statistics: Auto insurance — Insurance Information Institute (2025)Statistical dataNAIC countrywide average auto expenditure: $1,127 (2022), $1,282 (2023); most expensive states in 2023 were Florida, Louisiana and New York.
- Auto insurance for teen drivers — Insurance Information InstituteConsumer guidanceAdding a teen to a parent's policy versus a separate policy; good-student and driver-training discounts; vehicle choice.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- How much auto coverage do I need? — Insurance Information InstituteConsumer guidanceWhy state minimums are a floor; choosing liability limits that protect assets; when collision and comprehensive are worth keeping.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.