Guide
Staying on Your Parents' Car Insurance in College
The rules for remaining on a family policy as a college student—permanent address, car ownership, distance—and why it is usually the cheapest option.
By Sophie Lindqvist · Editor
Published · Updated
Answer in brief
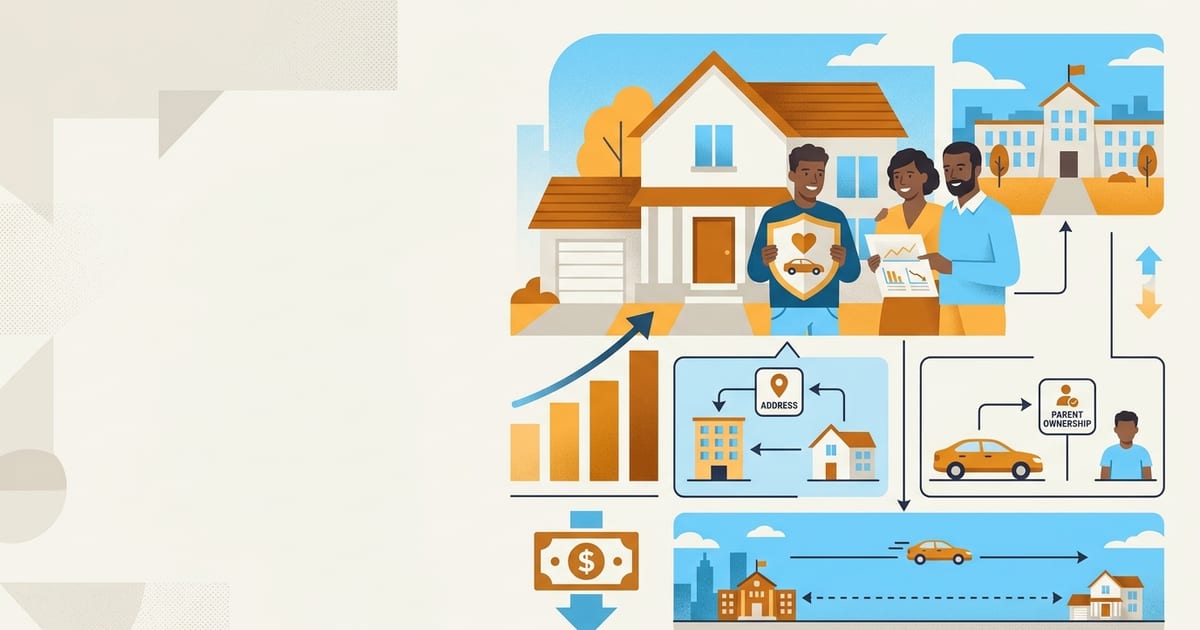
A college student can usually stay on a parent's policy as long as the family home remains their permanent address—a dorm or student apartment counts as temporary. It is almost always the cheapest option, often 40–60% less than a separate policy, because the student inherits household discounts and the parents' history. If the student takes a car to school, the insurer needs the campus garaging address. If the car is titled to the student, some insurers require the student to be a named insured. Students who move permanently, marry or finish school need their own policy.
Eligibility
| Situation | Stay on parents' policy? |
|---|---|
| Dorm or student housing, car stays home | Yes—ask for the distant student discount |
| Dorm or student housing, car at school | Yes, with campus garaging address updated |
| Off-campus apartment, still a dependent | Usually yes; the family home is the permanent address |
| Car titled to the student | Often yes if a dependent; some insurers require own policy |
| Out-of-state school with car | Usually yes; some insurers require a separate policy—ask |
| Graduated, moved out, working | No—own policy |
Why it is cheaper
The student benefits from multi-car and bundling discounts, the parents' long history, and occasional-driver rating. A separate policy for a 20-year-old starts with none of those and carries the full youth and inexperience factors.
What to tell the insurer
- Where the student lives during the term and whether a car is there.
- Distance from home (for the distant student discount).
- Grades (for the good student discount).
- Any change in who drives which car.
Quote finder
Find auto insurance quotes that fit your situation
When to leave
At graduation, when moving to a permanent address elsewhere, or when the insurer requires the car's title holder to be the named insured. By then the student has several years of history, which makes a separate policy far cheaper than it would have been at 18.
Entries in this guide
Specific questions answered in more depth.
Questions & answers
Can I stay on my parents' insurance if I live off campus?
Usually yes while you are a dependent and the family home is your permanent address.
Do I have to tell the insurer I'm at college?
Yes—to claim the distant student discount or to update the garaging address if the car goes with you.
Can I be on my parents' policy if the car is in my name?
Many insurers allow it for dependent students; some require you to hold your own policy. Ask.
Terms used in this guide
- Permanent address
- The address a student considers home and returns to; usually the family home while a dependent. Determines eligibility to remain on a parent's policy.
- Household member
- A person living at the insured address. A dependent student away at school typically still counts.
- Named insured
- The policy owner. Some insurers require a car's title holder to be a named insured.
- Garaging address
- Where the car is kept overnight most of the year; sets the rating territory. Must be the campus address if the car is at school.
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Teenagers — Insurance Institute for Highway SafetyIndependent researchTeen crash risk, graduated driver licensing research and vehicle recommendations for young drivers.
- Facts + Statistics: Teen drivers — Insurance Information InstituteStatistical dataCrash and fatality statistics for drivers 16–19 and graduated licensing context.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- Consumer insurance information — National Association of Insurance CommissionersConsumer guidancePlain-language guides from the body of state insurance regulators; links to every state's insurance department and complaint process.
- Auto insurance for teen drivers — Insurance Information InstituteConsumer guidanceAdding a teen to a parent's policy versus a separate policy; good-student and driver-training discounts; vehicle choice.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Guide
The Distant Student Discount
How the distant student (student away at school) discount works: the 100-mile rule, no-car requirement, typical savings, and how to claim it.
Guide
Taking a Car to College: Insurance Changes
What changes when a student takes a car to school—garaging address, territory, campus parking risk, comprehensive coverage, and who else may drive it.
Guide
Car Insurance for Out-of-State College Students
How insurance works when a student attends college in another state—keeping the home policy, coverage minimums, registration questions, and when a separate policy is needed.